Storm Claims
How to File a Roof Insurance Claim for Hail Damage in Texas: Nine Steps for Fort Worth Homeowners
From the first photos in the yard to the depreciation check, here is the order a Texas hail claim runs in, the deadlines your insurer works under, and the deductible rule no contractor may bend.
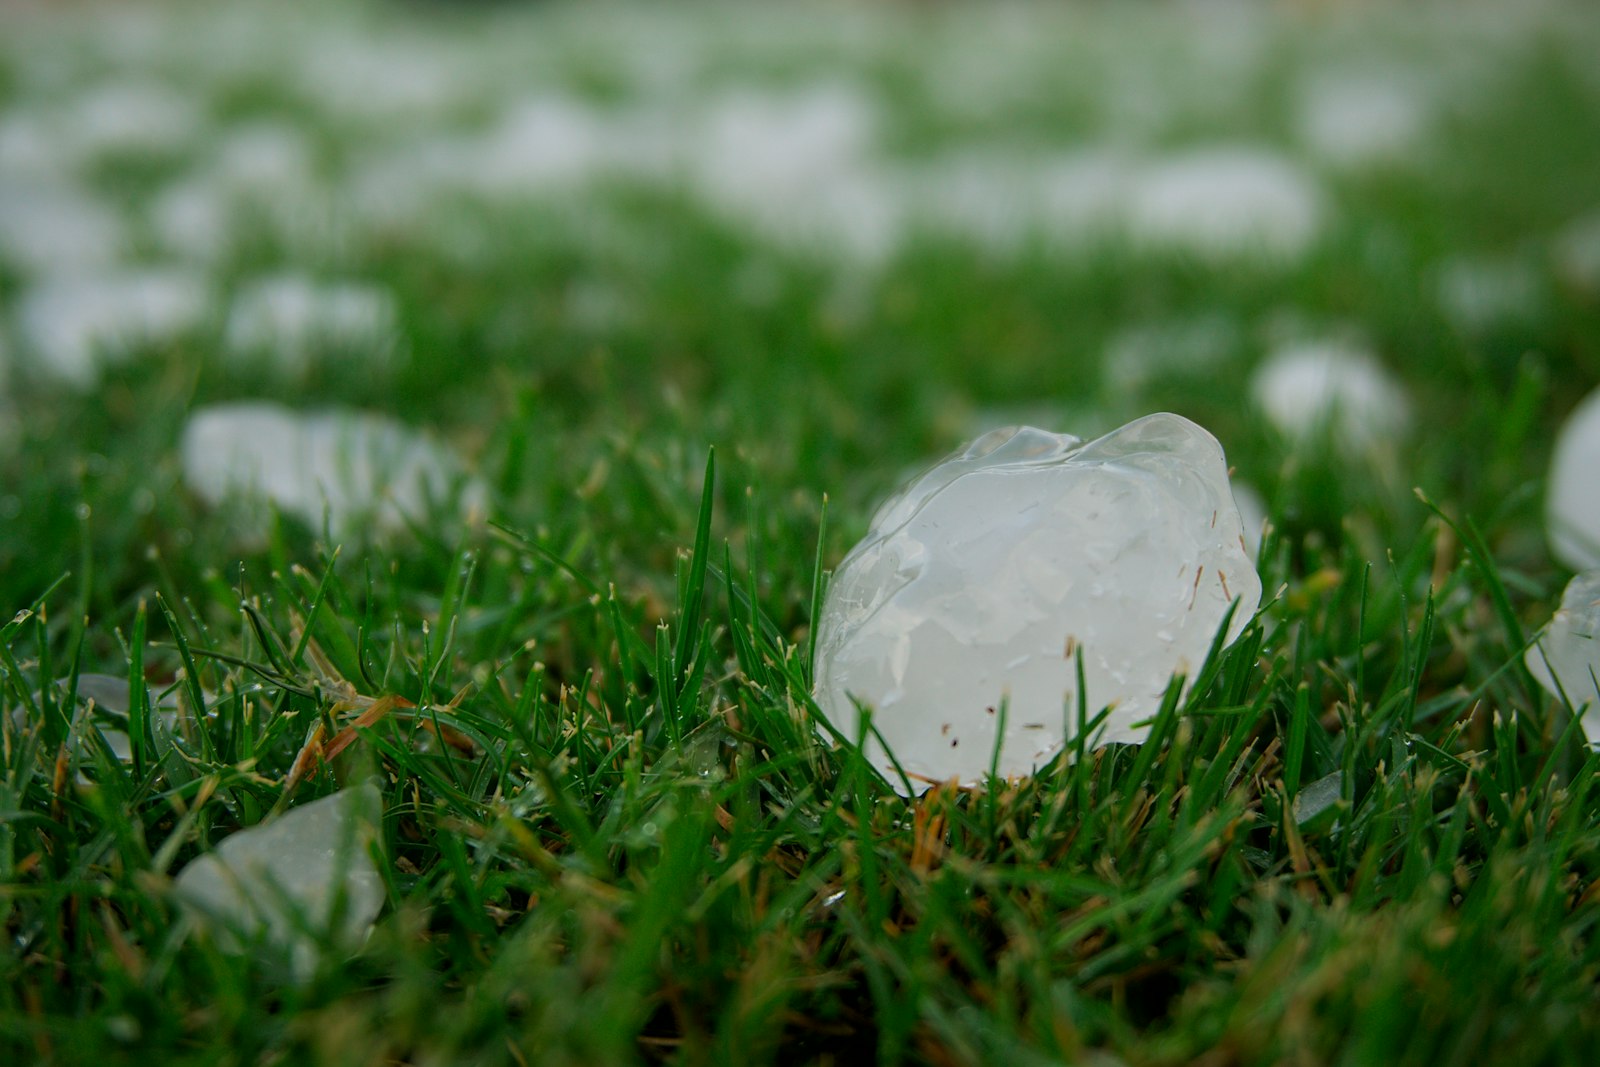
Fort Worth has a long memory for hail. On May 5, 1995, a storm dropped stones up to the size of softballs on the Mayfest crowd along the Trinity River, and the National Weather Service in Fort Worth puts the damage across Tarrant and Dallas counties at an estimated $2 billion. Most spring storms are smaller than that, but the paperwork that follows them is the same. A roof insurance claim for hail damage in Texas runs on photographs, policy language and a few statutory clocks, and homeowners who know the order of operations tend to have a calmer time of it.
What follows is general information, not legal advice. Your policy and your insurer control the details, and a dispute over money belongs with a licensed professional.
1. Photograph the storm and the yard before anything is cleaned up
The first evidence in a hail claim is usually on the ground, not on the roof. Before you rake, mow or hose anything off, take dated photos of hailstones next to a coin or ruler, dented mailboxes, split window screens, pocked patio furniture and marks on the car. Adjusters compare this collateral damage against what they find on the shingles, so it supports the story the roof tells.
Write down the date and approximate time the storm passed, then save any local weather alert or news report that names your part of town, whether that is Wedgwood, Ridglea, Fairmount or a street off Loop 820. Stay off the roof yourself; you do not need to climb to start a file.
2. Read the hail and roof terms in your policy before you call
Your declarations page tells you most of what shapes the payout. Look for the deductible that applies to wind and hail, and note whether it is a flat dollar amount or a percentage of your dwelling coverage, because the two can produce very different out-of-pocket figures on the same roof.
Next, find how the roof is valued. According to the National Association of Insurance Commissioners, actual cash value coverage pays based on the property's value considering its age and wear and tear, while replacement cost coverage pays to repair or replace it with materials of like kind and quality. Some policies settle roofs differently from the rest of the house, or exclude purely cosmetic damage, so read any roof endorsement line by line. Finally, check the notice requirement: your policy sets how quickly a loss must be reported, and waiting weeks to call makes the cause harder to tie to one storm.
3. Get an independent roof inspection before the adjuster visits
An inspection before the adjuster arrives tells you what is actually up there, so the meeting becomes a comparison rather than a surprise. A contractor walking every slope can photograph impact points, check soft metals like vents and flashing, and note gutter and siding damage that belongs in the same claim.
Fort Worth Roofing Texas offers a free roof inspection that is walked rather than viewed from the driveway, and the photographs are yours whether or not you hire the company. That photo set becomes part of your own claim file. If the inspection turns up an open leak, ask for a temporary repair or tarp and keep every receipt. Policies generally expect you to take reasonable steps to stop further damage, and those costs are usually submitted with the claim.
4. Report the claim and keep a written log of every contact
Filing the claim starts the insurer's legal clock, so report it through your carrier's app, website or claims line as soon as your photos are organized. Write down the claim number, the date you reported it, and the name of everyone you speak with.
Under the prompt-payment provisions of Texas Insurance Code Chapter 542, a standard insurer generally has 15 days after receiving notice of a claim to acknowledge it, begin its investigation and request the items it needs from you. Eligible surplus lines insurers get longer. Answer document requests quickly and in writing, because several of the later deadlines only begin once the insurer has everything it asked for.
5. Meet the adjuster on the roof, not just at the front door
Being present for the adjuster's inspection is the single easiest way to keep the scope accurate. Have your own photos ready, point out the collateral damage you documented, and ask the adjuster to look at every slope, including the ones not visible from the street. If your contractor attends, their role is to show what they documented, not to argue coverage.
Ask how the adjuster plans to account for code items. The City of Fort Worth's residential roofing FAQ says drip edge and crickets are required during reroofing if they are not already present, and that a permit is required when decking is replaced, though not when only shingles are. Whether those costs are paid depends on your policy, so ask whether you carry ordinance or law coverage. Request the adjuster's written estimate and compare it line by line with your contractor's scope once it arrives.
Want your hail damage on record before the adjuster comes?
We walk each slope, photograph the impact points and soft metals, and write up what we find. You keep the photo set for your claim file, whoever you hire.
Schedule a post-storm look — (682) 399-87896. Know the deadlines Texas places on your insurer
Texas law gives the insurer firm windows to decide and to pay. Once it has received all the items, statements and forms it requested, a standard insurer generally must accept or reject the claim within 15 business days. If it needs more time, it must tell you so within that window and then decide within 45 days of that notice.
After the insurer tells you it will pay, the payment itself is generally due within five business days. When the commissioner declares a weather-related catastrophe, Chapter 542 extends these claim-handling deadlines by an additional 15 days.
7. Read the settlement carefully: ACV first, depreciation later
A replacement cost policy often pays in two parts. The first check usually reflects actual cash value, meaning the replacement estimate minus depreciation and minus your deductible. The withheld depreciation, often called recoverable depreciation, is released once the work is completed and documented.
Texas ties that second payment to your deductible. House Bill 2102, which added Insurance Code Chapter 707 in 2019, lets an insurer that issues replacement cost coverage withhold recoverable depreciation until it receives reasonable proof that you paid the deductible, such as a canceled check, money order receipt, credit card statement or executed financing contract. Also check whether your mortgage company is named on the check, because it may need to endorse it before the funds can be used.
8. Pay your own deductible and walk away from any offer to cover it
In Texas, the deductible is legally the homeowner's to pay. The same 2019 law states that a person insured under a property policy shall pay any deductible on a first-party claim, and it amended Business and Commerce Code Section 27.02 to make it an offense for a seller to pay, waive, absorb or rebate that deductible, or to advertise doing so, without the insurer's consent. A violation is a Class B misdemeanor.
- No credit for a sign in your yard or an unrelated discount sized to offset the deductible.
- No invoice that pads the price to cover what you owe.
- Contracts of $1,000 or more expected to be paid from insurance proceeds must carry a 12-point bold notice that Texas law requires the insured to pay the deductible.
- A contractor can document and scope damage, but should not negotiate your claim or interpret your policy.
Fort Worth Roofing Texas states plainly that it documents and scopes storm damage and does not negotiate claims, interpret policies or absorb deductibles. That is the line every compliant contractor in Texas should hold.
9. Ask for a re-inspection in writing if the scope falls short
A short scope is best answered with documentation. If the adjuster's estimate leaves out slopes, vents, gutters or code items your contractor found, send the insurer those photos and the line-item scope and ask in writing for a re-inspection or a supplement.
Many policies also contain an appraisal clause for disagreements over the amount of loss, and the Texas Department of Insurance accepts consumer complaints. A dispute that stays stuck is a reason to speak with a licensed attorney or public adjuster, not your roofer.
What to Do This Week If Hail Just Hit Your Street
Do three things before anything else: photograph the yard and roof edges while the evidence is fresh, find the wind and hail deductible on your declarations page, and get the roof walked by someone who will hand you the photos. Report the claim once those are in hand, then let the written log carry you through the adjuster meeting and the deadlines. Avoid the shortcuts, especially anyone at your door offering to make the deductible disappear. In Texas that offer is a crime, and it can put the depreciation payment you are owed at risk.
If you would rather have the documentation handled by a local crew, Fort Worth Roofing Texas can walk the roof and write the scope through its storm and hail damage roof repair service, starting with a free inspection. For general roofing questions, the Fort Worth Roofing Texas homepage is a good place to begin.
Sources and Further Reading
Hail Came Through Your Neighborhood?
Call before the adjuster visit and we will document the roof slope by slope, so you go into the claim knowing exactly what the storm left behind.
(682) 399-8789Call about storm damage — (682) 399-8789